You can be an excellent therapist, build a thriving practice, and still feel unprepared when your tax bill arrives. Clinical training rarely covers the financial responsibilities of business ownership, leaving many therapists to learn as they go. In this episode of The Practice of Therapy Podcast, Gordon Brewer welcomes Kemy Akati, CPA, to discuss how practice owners can approach their finances with more clarity and less overwhelm. From organizing business transactions to asking better questions about tax planning, Kemy shares why getting support before tax season can make a meaningful difference.
Meet Kemy Akati 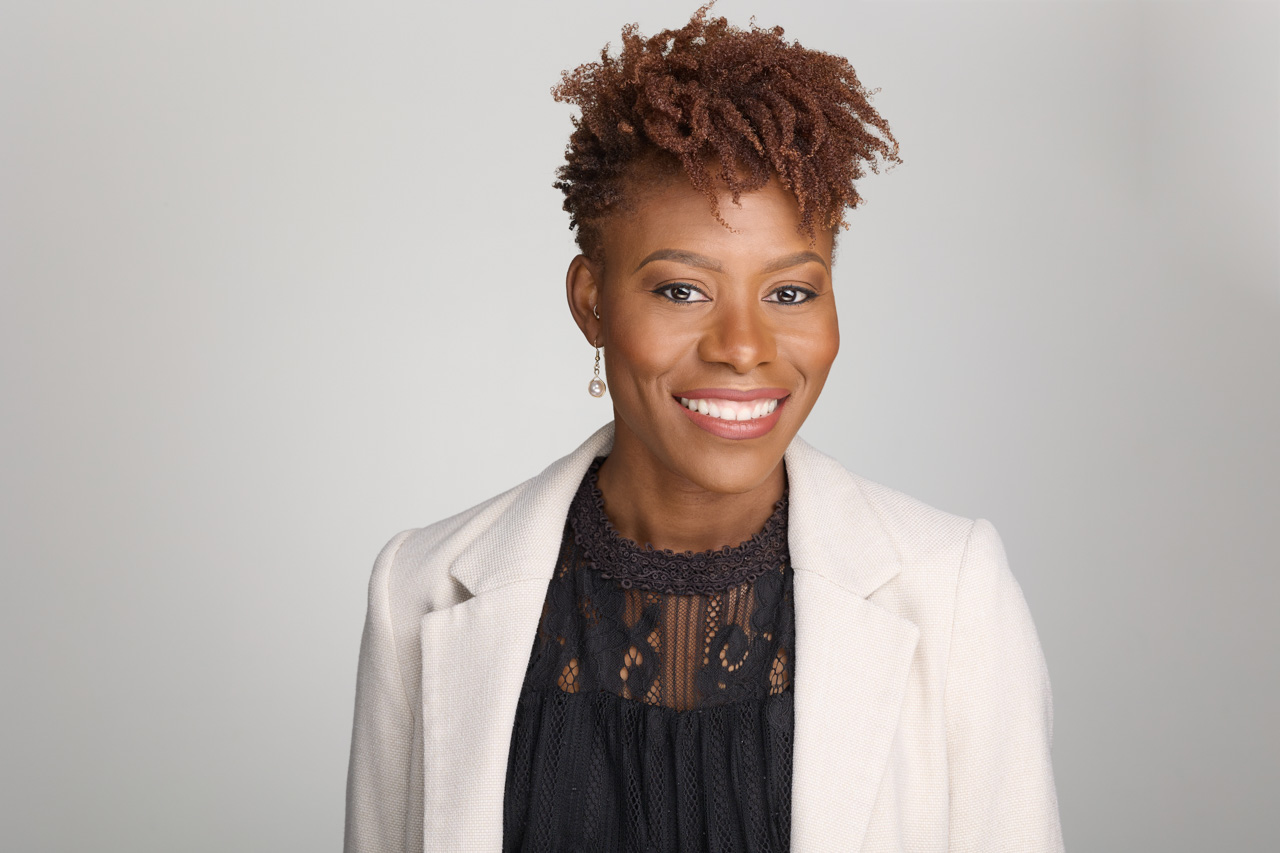
Kemy Akati, CPA, helps therapy practice owners stop dreading tax season. With over a decade of experience as a CPA, she runs Arrow Accounting, a virtual practice focused on tax strategy and advisory for group practice owners. Instead of just filing returns, Kemy works alongside owners all year to build a plan, so they know what they’ll owe, keep more of what they earn, and make decisions with confidence. Learn more at https://www.arrow.cpa or connect with Kemy on LinkedIn.
Tax Planning Starts Before April
One of the biggest mistakes Kemy sees is waiting until April to start thinking about taxes. By then, the previous tax year has ended, and many opportunities to plan ahead have passed. She compares it to helping a client prepare for a panic attack: coping strategies are easier to put into practice when you have discussed them before the crisis. For practice owners, that preparation means having conversations throughout the year about income, anticipated taxes, and upcoming decisions. With the holidays bringing additional expenses, knowing what to expect can also help prevent a tax bill from becoming another financial surprise.
Start with a Clear Record of Your Business Finances
When bookkeeping feels intimidating, Kemy encourages practice owners to begin with a simple foundation: a separate bank account for business transactions. Paying expenses from several personal accounts or credit cards makes it harder to understand what is happening in the practice. Keeping business income and expenses together creates a clearer record and makes it easier for a bookkeeper or accountant to help. Kemy also emphasizes keeping receipts and supporting documentation. As the practice grows, bookkeeping software can help organize those records and give the owner a more useful picture of the business.
Prepare Your Systems Before You Hire
Adding clinicians introduces financial responsibilities that are easier to manage when the right systems are already in place. Kemy discusses the importance of understanding employee and contractor classifications, collecting the appropriate information, and setting up payroll when needed. Waiting until the end of the year to track down missing paperwork adds unnecessary stress. For therapists moving from solo to group practice, this is an opportunity to get professional guidance before hiring decisions create administrative problems.
Your Tax Strategy Should Fit Your Practice
Practice owners often want a straightforward answer about when to consider S corporation taxation. Kemy’s response is to look at the individual situation and run the numbers. Potential savings need to be weighed against additional costs, payroll responsibilities, reasonable compensation requirements, and state-specific considerations. A strategy that works well for one owner may not make sense for another. Her broader message is that tax planning should account for the whole picture, including the practice, the owner’s personal goals, and the work involved in maintaining the arrangement.
A Deduction Is Only Part of the Picture
Kemy and Gordon also explore expenses that practice owners may want to discuss with their tax professional, including therapy supplies, professional education, business travel, mileage, and home office use. Kemy repeatedly returns to the importance of documentation and meeting the applicable requirements. An expense’s connection to the business needs to be supported, not simply assumed. Keeping organized records throughout the year makes those conversations easier and helps an advisor evaluate what is appropriate for the practice.
Your Time Matters, Too
Some tax strategies sound appealing until you consider the effort required to carry them out. Kemy shares examples of conversations about incorporating business activities into travel or paying children for legitimate work in a practice. Her point is to consider both the potential savings and the responsibilities involved. A strategy may require tracking time, maintaining additional records, or changing how you spend a trip. Gordon notes that the time spent pursuing savings has value, too. A useful plan should support your goals without adding more complexity than you want to manage.
Move from Overwhelm to a Plan
For Kemy, successful tax planning is about more than finding savings. It is also about helping practice owners feel informed and prepared. You do not have to become a tax expert to take a more active role in your finances. Getting organized, asking questions early, and working with someone who understands your practice can help you make decisions with greater confidence.
Gordon Brewer: Well, hello everyone, and welcome again to the podcast.
And I'm really looking forward to you hearing from Kemi Akati Welcome, Kemi. Glad you're here.
Kemy Akati, CPA: Thank you. Glad to be here.
Gordon Brewer: Yes. A- and Kemi is a CPA, and we're gonna be talking today about tax season, which will be here before we know it, and how we can prevent some overwhelm with all of that. But Kemi, as I start with everyone, tell folks a little bit more about yourself and how you've landed where you've landed.
Kemy Akati, CPA: Yeah. So thank you so much for having me again, Gordon. Um, so I'm Kemi Akati I'm a CPA and owner of a firm here in Powell, Ohio. So I specifically help therapy practice owners stop dreading tax season. Um, so what I've noticed is that most of my clients, they're group practice owners, they're amazing clinicians.
They've built something real that they're proud of, but every April they feel blindsided or surprised by a tax bill they didn't see coming. And so what I do is replace that overwhelm and doubt, um, with a plan. So we can look at the whole picture, the practice, the entity, the owner's personal goals and we decide ahead of time how much do we wanna keep and what can we do to keep that.
Um, my clients tell me that the biggest change that they've seen is not just in the tax savings, but really they just finally feel at peace and secure with their finances and their tax situation.
Gordon Brewer: Yeah, and I know that the people that have been listening to this podcast for a while know how I tend to harp on the importance of knowing your numbers and knowing, understanding, you know, just kind of the financial side of running a practice, because most of us, um, get really good clinical training, but really n- little to no business training and no, or any understanding of all of that.
Kemy Akati, CPA: Yeah.
Gordon Brewer: Yeah.
Kemy Akati, CPA: I would say that that's pretty accurate, yeah, in most professions actually, you know?
Gordon Brewer: Oh, right. So what, it, I guess maybe a, a way for us to start out here with this conversation, what is it that you notice that, um, maybe some mistakes that ther- therapy practice owners make when it comes to thinking about tax season and, what are the starting steps to kind of get a handle on that?
Kemy Akati, CPA: I would say, you know, that's a question that I get a lot. I would say that the biggest thing is waiting until April 1st, right? Mm-hmm. To kinda... You know, that's really when people wake up and they decide, "Oh, yeah, it's time to file taxes." By April, it's too late. Um- Mm-hmm ... I like to think of it kind of like if you have if you have a client who's prone to have, like, panic attacks or something like that, you know?
You don't wanna wait until they're mid- in the middle of the panic attack to give them a plan or a strategy to cope and deescalate, right? You wanna do that beforehand. You wanna plan ahead of time to be able to notice the warning signs so that when it's coming on, they can kinda react in the moment.
So that's how I kind of see it. Waiting till April is like you're already in the panic attack. You're just gonna have to- Mm-hmm ... like, ride it through. Planning ahead of time during the actual tax year before December 31st is the best time to start thinking about taxes. Mm-hmm. So I would say that's the mo- number one thing, waiting too long.
I would say the second thing is not estimating how much you might owe, right? Because, we have holidays, Thanksgiving, Christmas, like, New Year, all of that, a lot of people are doing a lot of cash outlay, and so it's really usually a big shock a couple of months after that to have another huge cash outlay.
So if you can plan during the year, then you can kinda, like, figure out, "Okay, let me put this aside. Let me pay this. Let me do that," so that the beginning of your new year is a little more smooth by the time you get to April 15th.
Gordon Brewer: Yeah. Yeah. So i- if pe- as people are listening to this, what are some things that probably they, if they've not done any preparation for this, like you said, if they typically waited till the last minute, you know.
You know, I've, I've heard s- numerous stories of people, you know, doing that, and then when they get their taxes done, they realize, "Oh, my gosh, I owe this huge tax bill." Yeah. And, um, they're not prepared for it. But what are things that people should be doing right now, um, to begin to prepare?
Kemy Akati, CPA: Well, I would say number one is honestly every situation is different, and so I would always recommend getting a tax planning advisor.
Get a CPA who can plan with you. Um, if you're in the place where you're still thinking, "Well, I don't know if I'm ready for that. What can I do on my own?" The IRS has something called safe harbor, which is, like, if you pay at least... There's different percentages based on your income, but if you pay about 110% of last year's taxes during the year, then if you end up owing more by April 15th, then there's no interest or penalties because you've at least done the minimum.
So that's one thing- Mm-hmm ... I would say to people. If you, if you're not sure, at least pay 110 of the prior year ahead of time- Mm-hmm ... both in federal and also in the state that you're in if you have state income taxes. Mm-hmm. Those are just some easy things you can do to kinda get yourself settled, Mm-hmm
as it relates to paying for taxes. I would say in addition to that, having proper bookkeeping is essential- Mm-hmm ... and I would say the foundation of that is even just having a business bank account. So I know a lot of people start off and they may not have an LLC yet, which you should have an LLC in the beginning.
Mm-hmm. But even if you don't have an LLC, you can even just create a separate bank account in your own name that you can do only business transactions in there, all the income there, all the expenses. That is really important because it separates you from the business. And so if you do get help later on, like a bookkeeper or a tax advisor, we're able to take that and run with it without having to separate it out from all the other personal things that you have done.
So those are a few things I would recommend to people to do aside from just getting the help that they need.
Gordon Brewer: So what, what are some of the, other than obviously another bank account or whatever, what other, other systems do people need in terms of bookkeeping? I know there's lots of different ways people can do- Yes
bookkeeping as far as, you know, doing something like QuickBooks or one of the other accounting softwares- There's, you know, yeah ... or even just y- or using, um, something like, uh, just a spreadsheet or something I think is probably- Yeah ... better than nothing, yeah.
Kemy Akati, CPA: Yeah. I know it sounds so simple, but honestly just having a bank account is the easiest way to start.
Mm-hmm. Because it is a record of everything you've done. 'Cause even if you do one on a spreadsheet, how do I know that it actually happened, right?
Gordon Brewer: Like,
Kemy Akati, CPA: so for me, I'm always looking at the track record. How can I prove this income? Well, if you see the deposits in your bank account, you can prove it.
How can I prove this expense? Okay, there's transactions. Of course you need to keep your receipts. So I always go to the path of least resistance, right? So for those that are like, "I don't like numbers, I don't wanna do any of this," have a bank account where everything's tracked. When you do get the help, you can just dump it all in there and we can categorize it.
Mm-hmm. So I always kind of go back to that 'cause it's the simplest way. And it's ha- again, you can't do that easily if you're paying from different sources, like from your personal credit card and from- Mm-hmm, mm-hmm ... your husband's account and all these other places where it's not centralized. Mm-hmm. So if someone is not yet gonna be on a bookkeeping platform or whatever, at the very minimum have a bank account, everything is tracked there, we can always go back after the fact to track and categorize everything.
Mm-hmm. Right. I think it's, I would prefer that over a spreadsheet. You can do a spreadsheet, but having the source record I think is
Gordon Brewer: easier to track. Right. So yeah, so in, in working with people, how do you begin setting everything up as far as good bookkeeping and that sort of thing? You know, obviously- Bank account
the bank account. Right. Yeah. But, uh, just thinking beyond that, if somebody wants to-
Kemy Akati, CPA: Yeah ...
Gordon Brewer: do something a little more than that, particularly as they- Oh, yeah, yeah ... grow and they start maybe adding clinicians and employees and all of that kind of things.
Kemy Akati, CPA: Yeah. So for sure- Mm-hmm ... you need a bookkeeping software.
QuickBooks is really popular. I know Xero is another really good software as well to use to set up the- Mm-hmm ... bookkeeping. That will help you have everything going through and tracked as well. When you're at the point where you're hiring other clinicians, you wanna make sure that is it, is this clinician an employee or a contractor?
Mm-hmm. There are specific IRS rules for that of, like, what determines who an employee is versus a contractor, so you wanna be mindful of that. We don't just get to decide who's a W-2- Mm-hmm ... versus a 1099. And a lot of that is making sure you collect the W-9 form ahead of time before you begin paying them, because it is your that, you know, that's if they're a 1099, or making sure you set up the proper payroll, because as the employer or the company providing the 1099, it is your responsibility to make sure that you file those forms at the end, and you can't do that unless you've collected information from them before.
Are you paying them to their EIN? Are you paying them to their Social Security number? You gotta know that upfront. I see a lot of, Practice owners not doing that and then kinda chasing that information after the fact at year-end- Mm-hmm ... which makes it a little bit complicated to be able to meet all the deadlines, um- Right
that are in place. So just setting it properly ahead of time is gonna be really helpful with the hiring part of it.
Gordon Brewer: What sort of guidelines do you like to give people around just planning for their self-em- but that's another thing is just self-employment tax- Self-employment ... is much different than if you're working for someone where you're getting a W-2, um, because you've got to pay, actually pay more as a self-employed person.
Kemy Akati, CPA: It's like 15.7%, I think.
So basically in addition to the safe harbor... Well, it depends. If you've been in practice for a while and you've paid self-employment tax before, the safe harbor calculation I gave earlier, 110% of the prior year, should help you kind of cover that.
But yeah, self-employment taxes are about an additional 15% of taxes. If you're in a place where you're feeling like, "Wow, that's a lot I'm paying in taxes," the self-employment tax is growing, then it might be time for you to consider a separate entity, like an S corporation and things like that. And it really varies based on where you're at, your outlook for the year, whether it's the right time to make that move or not.
I know with me I like to just run the numbers, 'cause you don't really know until you look at your actual numbers or your estimated numbers to figure out like, "Okay, should I keep planning to pay for this additional 15%, or is it time for me to have a plan in place to not have to pay this additional 15% and cut it down significantly?"
Mm-hmm. I know earlier this morning I actually just had a call with one of my clients, and in our planning, we're looking to be saving about $10,000, right?
Gordon Brewer: Mm-hmm.
Kemy Akati, CPA: Just from making that move alone. And so again if you're at the point where you're like gosh, this is a lot that I'm paying," have a conversation- Mm-hmm
to figure out sh- am I supposed to keep paying this or is there a way to save on that?
Gordon Brewer: Yeah. What's, uh... You know, I had heard in the past that, um, when your gross income, in other words, everything that you take in, reaches a certain point that's where would maybe be the, the place to determine whether or not an e- you should switch to being an S corp, be- being taxed as an S corp versus as a, you know, a disregarded entity or, you know, those kinds of things.
Yeah.
Kemy Akati, CPA: So I like to think of it, hopefully this is a helpful analogy. If you had a client- Mm-hmm ... come into of- your office on the first day and they're like, I am thinking about divorcing my spouse. Should I do it or not?" It would be, I would not want a therapist to give me a blanket answer of yes or no, right?
Mm-hmm. Mm-hmm. 'Cause you gotta look into the situation. Maybe this is just a communication issue that can be worked out. Maybe they just need tools, or maybe this really is an abusive situation where they need to get away, right? And so every case is different. You gotta get with somebody who can help you kinda analyze.
I wouldn't say that that number would be a blanket number. I would say that when you start feeling like, "I'm paying too much, I can't plan enough for it I I'm... this is more... I'm needing more support than just filing my taxes. Like, I feel like there's something off, and I can't quite figure out what it is.
It's overwhelming." I feel like that's when I see people kind of reaching out, 'cause they're like, "This is ballooning into something bigger, and I need help." Mm-hmm. And then we can analyze that. The reason I say that is because there are additional costs to switching an entity. Why you gotta f- Mm-hmm ... you gotta file it with the IRS, you gotta start running payroll, you gotta figure out reasonable compensation, and how much are you actually saving?
And is the cost- Mm-hmm ... of doing all that gonna be worth the savings? And so I always- Mm-hmm ... I always go back to running the numbers, and then, is there... Do you have other business ventures? In your state, does it make sense to do an S corp? 'Cause there are some states where, you know, once you fi- file another entity, you may have to pay separate taxes, because now you have a corporate tax to pay.
And it may not make sense- Mm-hmm ... for you to do that because of the jurisdiction that you're in. Mm-hmm. So it's hard to give a blanket answer. I would say run the numbers and figure out, does this make sense for me in this season that I'm in?
Gordon Brewer: Right. The thing is, is that you hear so many different things about tax advice, and I think a- as you p- Yeah
as you point out, it is so individualized to everybody's situation and that sort of thing. Yeah.
Kemy Akati, CPA: It is. Yeah. Mm-hmm. And you wanna work with somebody who can understand- ... exactly your situation and your, you know, your pain points may not be somebody else's pain points. Your concern- Mm-hmm ... may not be somebody else's concern.
Some, you know, some people are not... Sometimes to get tax savings, you have to go jump through so many hoops that it may not be worth it. Like I had- Mm-hmm ... a client who was, we were talking about, they were gonna travel out of state, uh, travel to Hawaii on vacation. And so they're like, "Hey, how can I is there a way I can deduct this?"
And so when I talk to my clients, I'm always like, "Yeah, the question is not can I deduct it, the question is how can I make it deductible?" So I kinda walk through- Mm ... okay, if this criteria was in place, then you could make it deductible, but if this is truly a vacation, are you willing to do the work to make this deductible?
And at the end of the day, let's calculate how much you would actually be saving, and is it worth- Mm-hmm ... jumping through all these hoops to make this deductible? So in- Mm-hmm ... that might be valuable to someone else, but to you, you might be like, "I just want my vacation. I don't wanna prove that I was working half the day to make it a business expense," you know?
Right. So it goes back to what's important to you, right? I know some clients, you know, they may have children that are already working in the practice. They're helping them, doing a lot of the things. While it may make sense to wanna pay your child and figure out how to make that work, but maybe all the work you need to do to make that happen isn't worth it, right?
Like, oh- Mm-hmm ... I'm only saving, like, $500 in taxes. Is it worth it to track how much time my child is spending and figure out a job description for them? Well, maybe not. And so it really- Mm-hmm ... depends on each situation and what's important to each person.
Gordon Brewer: Yeah. Yeah. And I think that's a, you make a good point because, um, the time we spend on stuff is just as valuable as maybe the money that we spend on things, and we can spend a whole lot of time on things that really don't get us that much savings and money.
Kemy Akati, CPA: And I feel like- You know? ... that's a lot of the, the sort of s- so to speak tax loopholes and things that we hear about online.
Gordon Brewer: Mm-hmm.
Kemy Akati, CPA: Like, it can sound easy at first, like, but yet, let's just do this, but what it takes to prove that- is so much more- Mm-hmm ... that, you know, you really wanna consider is it worth my time or do I just wanna serve my clients?
So.
Gordon Brewer: Yeah. M- maybe to move to a little more specific question, um, you know, in therapy practices and our practices, we really don't have just a whole lot of overhead like we tend to think of as other businesses, certainly like a manufacturing business where they have costs of goods and all of those kinds of things which are tax write-offs or ways to save on taxes.
What are maybe some top places that maybe we don't think about that could be considered an expense or a deductible, that kind of thing, that you run into with therapy practices?
Kemy Akati, CPA: So my children have a play therapist. Mm-hmm. And anytime I go to his office, you know, he has this whole room with all these toys in there for them, right?
So there's, like, the chess board game, there's the handcuffs, There's, like, a punching bag thing- Mm-hmm ... to get the aggression out and the energy. And for a typical person, that would not be deductible. Like, I cannot deduct my chess board game in my business, but because he's using it for his practice, he can deduct that.
So you always wanna think about, like, what are the things that I am doing only for the business? What are the things that I'm purchasing for the business w- that have a business purpose? Those are the things that we can be able to deduct. Other things we think about is home office. Are you using a part of your home for the business?
You're entitled- Mm-hmm ... to get reimbursement for that. That's another one. Mileage. Are you traveling for the business? That's another thing that's deductible. Now- Mm ... we can lay out all of these things that's deductible, but I go back to proof. So basically, going back to just the general the general rule, right?
We know the IRS is like- Like, the Internal Revenue Code, the law is, like, thousands of pages long. The general premise is all income is taxable and no expenses are deductible. That's the general premise. Mm-hmm. But then you have a lot of exceptions after that. But in this case, you can deduct this, or in this case, this income is not taxable.
So it is your burden to prove that something is an exception, right? And so how can I prove that me getting a therapy animal for my clients is a business deduction? If I did that for my clients, it would not make sense in my practice 'cause I'm not a therapy practice owner, I do accounting. But if a therapy owner did that, then it would make sense, right?
So you wanna think about- ... is it a business purpose? Is it typical in my line of work? Do other practice owners also have these expenses and deductions? Do I have proof? Is there documentation? Did I actually pay for it? Is there a receipt? So tho- tho- those are the things you wanna analyze and see for your situation.
Mm-hmm. Can I be able to deduct these things? But yeah, I would say the most commonly missed ones are for sure home office, mileage, education, travel, the supplies and tools that you use any books that you may have that you recommend to your clients that you just buy so they can see. Just anything that you wouldn't do if you were not in practice.
Yeah.
Gordon Brewer: Yeah. I think that's... Yeah, so I think those things, they're getting creative with that, and again, that's where somebody like you, a CPA, can help with, "Okay, did you think about this?" 'Cause I-
Kemy Akati, CPA: Yeah ...
Gordon Brewer: you know, I know for me in the past, I didn't even think about my mileage, and, you know, anything that I go to work-related is a deductible thing- Yeah
um, if I have to drive. Yeah.
Kemy Akati, CPA: But it does matter how you do it, and that's the nuance- Mm-hmm ... and the caveat, 'cause I have heard- Mm-hmm ... horror stories. There's a gentleman, he's about to become a client of mine, so I had a phone call with him and he's like, "You know, I owe the IRS, like, $300,000." I'm like, "How?
What happened? Do you know?"
Gordon Brewer: Yeah. Mm-hmm.
Kemy Akati, CPA: So he's like, "Yeah, a couple years back you know, I claimed some mileage in my business." And so he claimed a ton of mileage. He didn't have support for it. And so not only did the IRS disallow that, they also disallowed the other business expenses that he could not support.
So all those- Mm-hmm ... deductions went away, and now he owed a ton. And so yes, there's a lot of things you can deduct, but how- Mm ... you support those is equally as important because- Mm-hmm ... if you don't have proof, it's as if it didn't happen. And so I always- Right ... go back to that, especially with things that are a little bit more nuanced, like mileage or home office.
You've gotta do it the right way. We can just- Right ... do those calculations. There's different rules, and the law- Mm-hmm ... keeps changing every year, so we gotta keep up with it and make sure. So I always caution, I, I've had some clients where I know they're legitimately taking mileage, but I just...
We won't write it off 'cause I'm like, "I- you don't have support, and I'm trying to protect you here." Mm-hmm. So-
Gordon Brewer: Right ...
Kemy Akati, CPA: and the savings it's giving you is so small, I don't want this to be a red flag, you know?
Gordon Brewer: Right.
Kemy Akati, CPA: So sometimes even if it's legitimate, you have to do it the right way. Right. It's really important.
Yeah.
Gordon Brewer: Yeah. You know, another, When, when you were talking about that, a- another area that people maybe forget to do, and I know that in working with my accountant this was something they reminded me of, is, uh, a health savings account. Um-
Kemy Akati, CPA: Yeah ...
Gordon Brewer: and being able to contribute to that throughout the year,
Kemy Akati, CPA: Yeah
Gordon Brewer: Can save you some money. Yeah.
Kemy Akati, CPA: Yeah.
Gordon Brewer: It was a few hundred dollars that it saved me by just contributing to that.
Kemy Akati, CPA: And it's actually really cool 'cause HSAs, it's not use it or lose it. It stays there. Mm-hmm. And so you may not have a need for it now, but maybe- Mm-hmm ... in the future you might. And now you have this...
It was never... It was income that was never taxed, and when it comes out, it won't be taxed if you use it for medical expenses.
Gordon Brewer: Mm-hmm.
Kemy Akati, CPA: And so that's... it's actually, like, a really cool savings vehicle for medical- Right ... expenses too, as well as offsetting your taxes today. So that's really
Gordon Brewer: cool. Right.
Kemy Akati, CPA: Yeah.
Gordon Brewer: Yeah. I love that. Yeah. Yeah. Well, Kemy, I know I've gotta be respectful of your time and just- Yes ... our time together, but tell folks how they can get in touch with you and ask more questions and just connect with you in general.
Kemy Akati, CPA: Yeah. So with anyone who's interested in just learning more about how to work with me, you can just go to arrow-cpa/call and then just set up a phone call, and we just have a conversation and see if we'd be a good fit to work together, just learn more about your situation.
Gordon Brewer: And tell folks your website again.
Kemy Akati, CPA: Yeah. Arrow, like an arrow that you shoot.
Gordon Brewer: Okay.
Kemy Akati, CPA: Arrow.cpa/call.
Gordon Brewer: Okay, awesome. And we'll have those links in the show notes- Yeah ... and the show summary for people to get to easily. But Kemy, it was great to meet you, and, uh-
Kemy Akati, CPA: Yeah ...
Gordon Brewer: thanks again for being on the podcast.
Kemy Akati, CPA: Thank you so much. I appreciate your time, Gordon.
Being transparent… Some of the resources below use affiliate links which simply means we receive a commission if you purchase using the links, at no extra cost to you. Thanks for using the links!
Kemy Akati’s Resources
Want what Kemy talked about today in your own practice? Book a complimentary 15-minute discovery call: http://www.arrow.cpa/call
Resources
 Use the promo code “GORDON” to get 2 months of Therapy Notes free.
Subscribe to our YouTube Channel
Start Consulting with Gordon
Listen to other great Podcasts on the PsychCraft Network Today!
Google Workspace (formerly G-Suite) for Therapists Users Group on Facebook
The Course: Google Workspace for Therapists
Follow @PracticeofTherapy on Instagram
Meet Gordon Brewer, MEd, LMFT
 Gordon is the person behind The Practice of Therapy Podcast & Blog. He is also President and Founder of Kingsport Counseling Associates, PLLC. He is a therapist, consultant, business mentor, trainer, and writer. PLEASE Subscribe to The Practice of Therapy Podcast wherever you listen to it. Follow us on Instagram @practiceoftherapy, and “Like” us on Facebook.